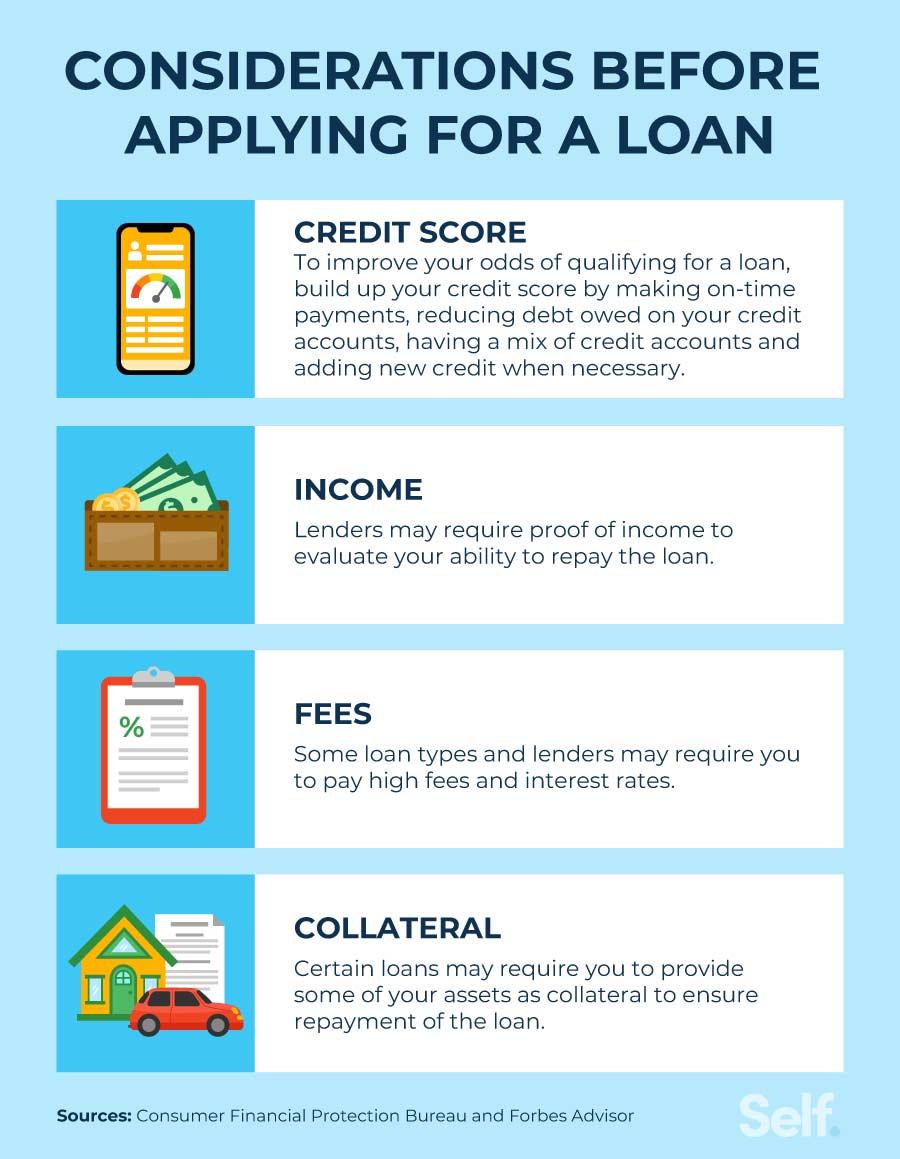
In at the moment's financial panorama, having poor credit can significantly restrict an individual's borrowing capacity, affecting their capacity to secure loans for numerous wants reminiscent of automobile purchases, residence renovations, or medical bills. This observational analysis article goals to examine the loans available for individuals with poor credit score, highlighting the challenges they face, the options out there, and the implications of these loans on their monetary health.
Understanding Poor Credit score
To really perceive the loans out there for poor credit borrowers, it is crucial to outline what poor credit score means. Sometimes, a credit score score beneath 580 on the FICO scale is considered poor. Elements contributing to poor credit scores may include late funds, high credit score utilization, bankruptcies, or having a limited credit historical past. Individuals with poor credit typically expertise increased anxiety when dealing with unexpected expenses, main them to hunt alternative financing solutions.
The Borrower's Dilemma
Individuals with poor credit score regularly encounter quite a few challenges when trying to find loans. Conventional banks usually hesitate to lend to borrowers perceived as high-danger, leaving these individuals with restricted options. They might resort to payday lenders or different alternative lending sources, which may allow them to access fast funds but come with exorbitant curiosity charges and unfavorable phrases. For a lot of, this cycle of dependency on excessive-cost loans can lead to a deepening debt spiral that further deteriorates their credit state of affairs.
Forms of Loans for Poor Credit
Regardless of these challenges, several loan choices exist for people with poor credit. This observational study identifies the most typical classes:
- Secured Personal Loans: These loans require the borrower to supply collateral, resembling a automobile or financial savings account, to safe the loan. The danger for lenders is diminished since they'll seize the collateral if repayments should not made. Secured loans often include decrease curiosity charges compared to unsecured loans.
- Credit score Union Loans: Native credit score unions have a tendency to supply more favorable lending phrases than traditional banks. They often focus on serving their neighborhood and should have specific applications tailored for individuals with low credit score scores, equivalent to small personal loans or second-chance credit score cards.
- Payday Loans: Whereas they provide fast entry to cash, payday loans include exceptionally excessive-interest charges and are usually due on the borrower's next payday. This feature is controversial due to the potential for borrowers to fall into a cycle of debt, making it a dangerous choice for those with already poor credit score.
- Peer-to-Peer Lending: Platforms like LendingClub and Prosper allow people to borrow cash instantly from different people. Borrowers are matched with individual investors who are prepared to lend funds, often at decrease rates than those provided by conventional lenders. However, rates still differ based mostly on the borrower's creditworthiness.
- Cosigner Loans: A cosigner with good credit score may help safe better loan phrases for a borrower with poor credit. The cosigner agrees to take responsibility for the loan if the primary borrower defaults, thus decreasing the perceived danger for the lender.
Implications of Poor Credit Loans
Whereas these loan choices can present instant financial relief, they come with significant implications. Borrowers might expertise heightened stress on account of high month-to-month funds or the concern of defaulting. The burden of sustaining loan repayments while managing dwelling expenses could lead to troublesome trade-offs, corresponding to sacrificing important needs. Moreover, if funds are missed, borrowers risk additional damaging their credit score scores, creating a vicious cycle that is hard to flee.
The Importance of Monetary Literacy
In our observations, an absence of financial literacy performs a pivotal function in the cycle of poor credit score and borrowing. Many individuals don't fully perceive the terms and situations of the loans they are entering into. Educating borrowers about curiosity rates, charges, and the lengthy-time period impacts of their loan selections can empower them to make extra knowledgeable decisions. Neighborhood workshops, on-line sources, and entry to monetary counseling are essential for equipping people with the information to navigate their financial conditions successfully.
Alternative Solutions
Beyond conventional loan avenues, we also noticed a shift in the direction of different options for people struggling with poor credit. Some social programs present direct financial help, providing grants or interest-free loans to these in need. Nonprofits resembling Operation Hope and the United Way are examples of organizations that advocate for low-earnings people by providing important financial schooling and assistance applications.
Case Research: Actual-Life Borrowing Experiences
For example our findings, we explored a number of case research of individuals with poor credit score looking for loans:
Case Study 1: Sarah's Journey
Sarah, a single mother with a credit score score of 550, confronted unexpected medical bills attributable to her kid's sickness. Though she initially thought of a payday loan, she opted for a credit score union loan as a substitute after attending a monetary literacy workshop. With a manageable interest rate, Sarah was in a position to repay the loan without falling deeper into debt.
Case Study 2: Mark's Struggles
Mark, who had a credit rating of 580, turned to a peer-to-peer lending platform. When you loved this post and you want to receive more info concerning loans for poor credit assure visit our web site. Although he secured a loan with increased interest than he would have liked, the funding allowed him to restore his automobile, in the end enhancing his job stability. Mark realized the significance of budgeting and started taking steps to enhance his credit score rating.
Conclusion
In conclusion, whereas poor credit creates vital hurdles for individuals in search of loans, numerous options exist to satisfy their financial needs. Each loan kind offers distinct benefits and disadvantages, necessitating careful consideration by the borrower. The societal challenge of poor credit score requires not solely elevated availability of loans for low-credit individuals but in addition academic efforts to improve financial literacy. By empowering people with knowledge, communities can help break the cycle of poor credit and pave the best way for a extra secure financial future.